Twitter Deal: Free Speech, LBO, and of course, Drama.
Table of contents
- Introduction
- Twitter before the deal
- How I tested the price
- Results
- What Musk’s behavior says
- Free speech: what I will track
- Conclusion
- Appendix
Introduction
$\rm\LARGE{T}$he bird is free, and now Musk has to pay for it. In my model of the deal, he put in about $28 billion of his own equity, including about $4 billion of shares he already owned, and the deal loaded $12.5 billion of debt onto Twitter. My base case returns about 4% a year, roughly what a 10-year Treasury paid when the deal closed. Even at the most generous exit multiple I tested, it reaches 17.3%, below the 20% to 25% that buyout investors target. The price only makes sense if Musk values something besides cash.
His first public message as owner was a note to advertisers promising that Twitter would not become a “free-for-all hellscape.” That tells me the economics are already shaping the free-speech project. Advertising produced about 89% of Twitter’s 2021 revenue, and advertisers avoid placing brands next to content they judge unsafe. A Twitter that moderates less will have to earn more of its money elsewhere, which is why I read Musk’s plan, announced on November 1, to charge $8 a month for Twitter Blue with verification as a necessity more than a feature.
I ask: Was Twitter a sound investment at Musk’s price, and if not, what does that tell us about why he bought it?
Claim
My claim has two parts:
i) At $54.20 a share, Twitter cannot earn a buyout-level return in any scenario short of a large outperformance.
ii) Musk’s own behavior between signing and closing points the same way: he tried three times to walk away from a price he had offered.
Twitter before the deal
Financial
Twitter’s revenue reached $5.08 billion in 2021, up 37% from 2020. Profits were another story. Twitter lost $221 million in 2021 and $1.14 billion in 2020, and it reported a net loss in eight of its ten fiscal years from 2012 to 2021.
Social
Twitter also carried controversies over content moderation, security and transparency:
- Content moderation. Twitter was accused of silencing conservative voices, most visibly in October 2020, when it blocked links to a New York Post story about Hunter Biden and then reversed the policy within days. Critics on all sides called its moderation decisions opaque.
- Security. A July 2020 hack took over about 130 high-profile accounts, including Barack Obama’s and Musk’s, to run a bitcoin scam.
- Transparency. Twitter was criticized for saying little about how its recommendation algorithms work.
In 2022, Peiter Zatko, Twitter’s former security chief, made serious allegations to Congress: weak controls over employee access to user data, exposure to foreign government interference, and a lack of candor about bots.
Musk bought this company at a high price and waived the usual due diligence rights. With a 10-year Treasury yielding about 4% when the deal closed, I wanted to know whether the price made sense as an investment at all.
How I tested the price
If Musk bought Twitter as a financial investment, a leveraged buyout model at his price should clear the 20% to 25% IRR that buyout investors typically target. So I built one. An LBO model fits this deal because debt paid for a quarter of it: the new owner repays the debt from Twitter’s cash flows during the holding period and keeps what is left at exit.
I modeled three operating scenarios over FY23 to FY31:
Particulars Downside Base Upside Advertising revenue mDAU growth rate 3% to 7% 8% to 15% 12% to 20% ARPU growth rate (2)% to 5% 0% to 6% 2% to 10% Twitter Blue subscription revenue Monthly fee growth rate 0% 2% 4% Existing subscriber renewal rate 90% to 92% 92% to 94% 94% to 96% New subscriber renewal rate 85% to 87% 87% to 89% 89% to 91% New subscribers, % of base 16% to 96% 18% to 98% 20% to 100% Operating expense growth rate 3% to 5% 3% 2% to 3% Exit EV/EBITDA multiple (FY29) 5x 10x 20x
Note: mDAU is monetizable daily active users; ARPU is average revenue per user.
I assume an exit by IPO at the end of 2029, about seven years after closing, because I doubt Musk could meet his financial or non-financial goals within a typical three to five year hold. I assume an IPO over a sale because the buyers big enough to pay, such as Meta or Alphabet, would face antitrust scrutiny.
Results
Sources and uses of funds
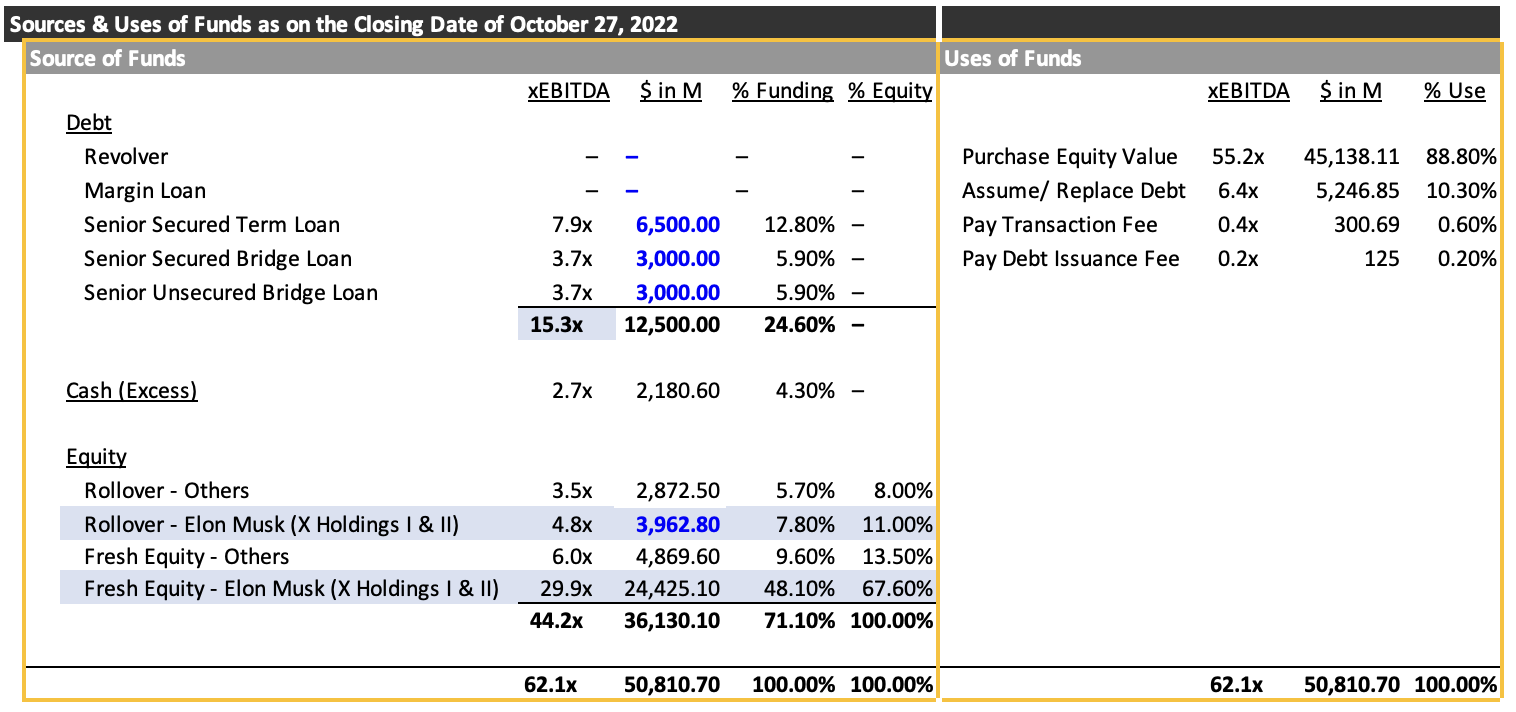
At closing on October 27, 2022, the deal needed about $50.8 billion. Equity paid for 71% of it, debt for 25% and Twitter’s own excess cash for 4%. Musk’s fresh equity alone was 48% of the total. Almost 89% of the money bought Twitter’s shares; most of the rest repaid Twitter’s existing debt.
Base case
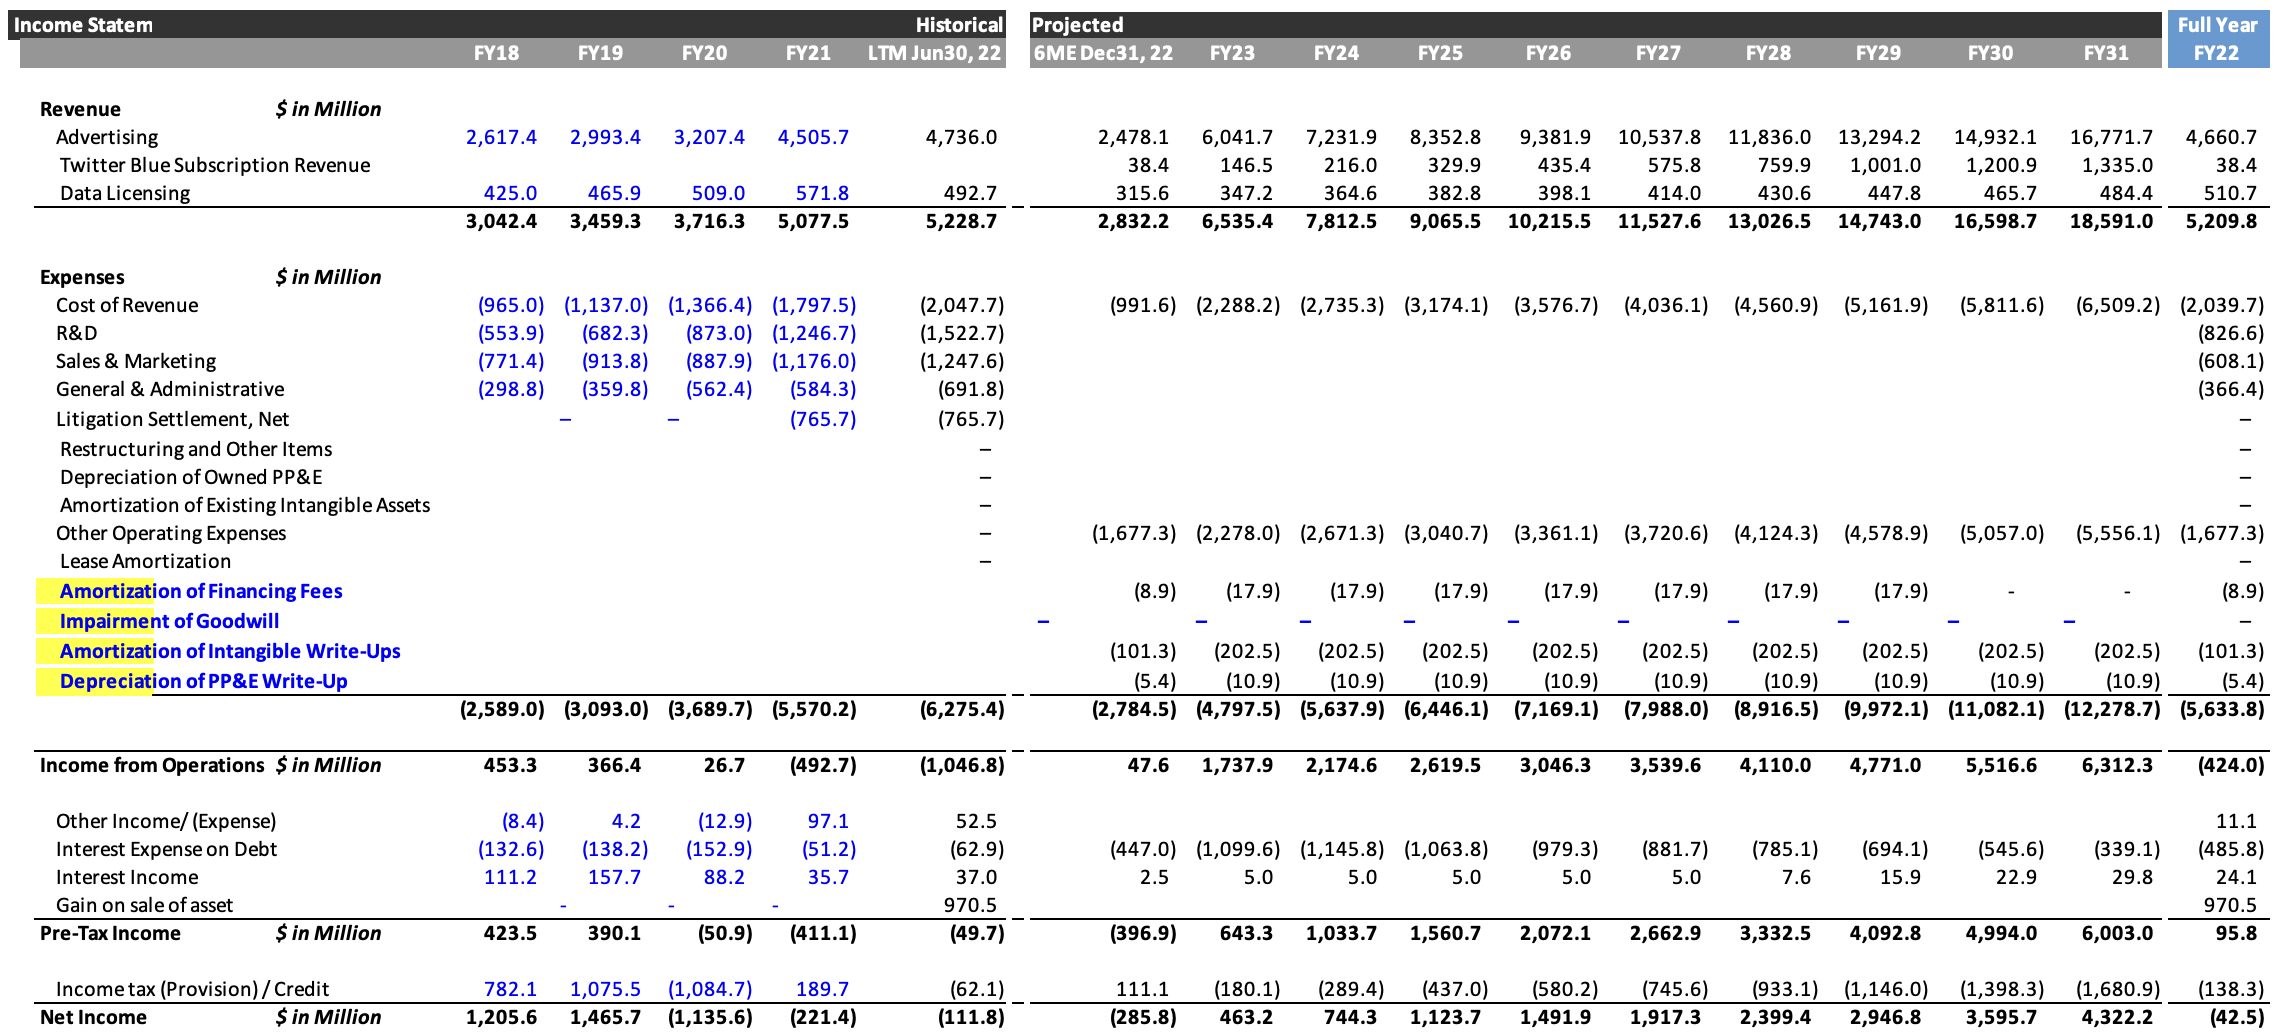
In my base case, revenue grows from $5.2 billion in FY22 to about $18.6 billion in FY31, mostly from advertising. Operating income turns from a $424 million loss in FY22 to $6.3 billion in FY31. Interest expense peaks at about $1.1 billion in FY24 and falls to $339 million by FY31 as the debt is paid down. Net income turns positive in FY23 and reaches $4.3 billion in FY31. This is a good business by FY31, and it still does not earn a buyout return, which is the point of the next table.
Downside case
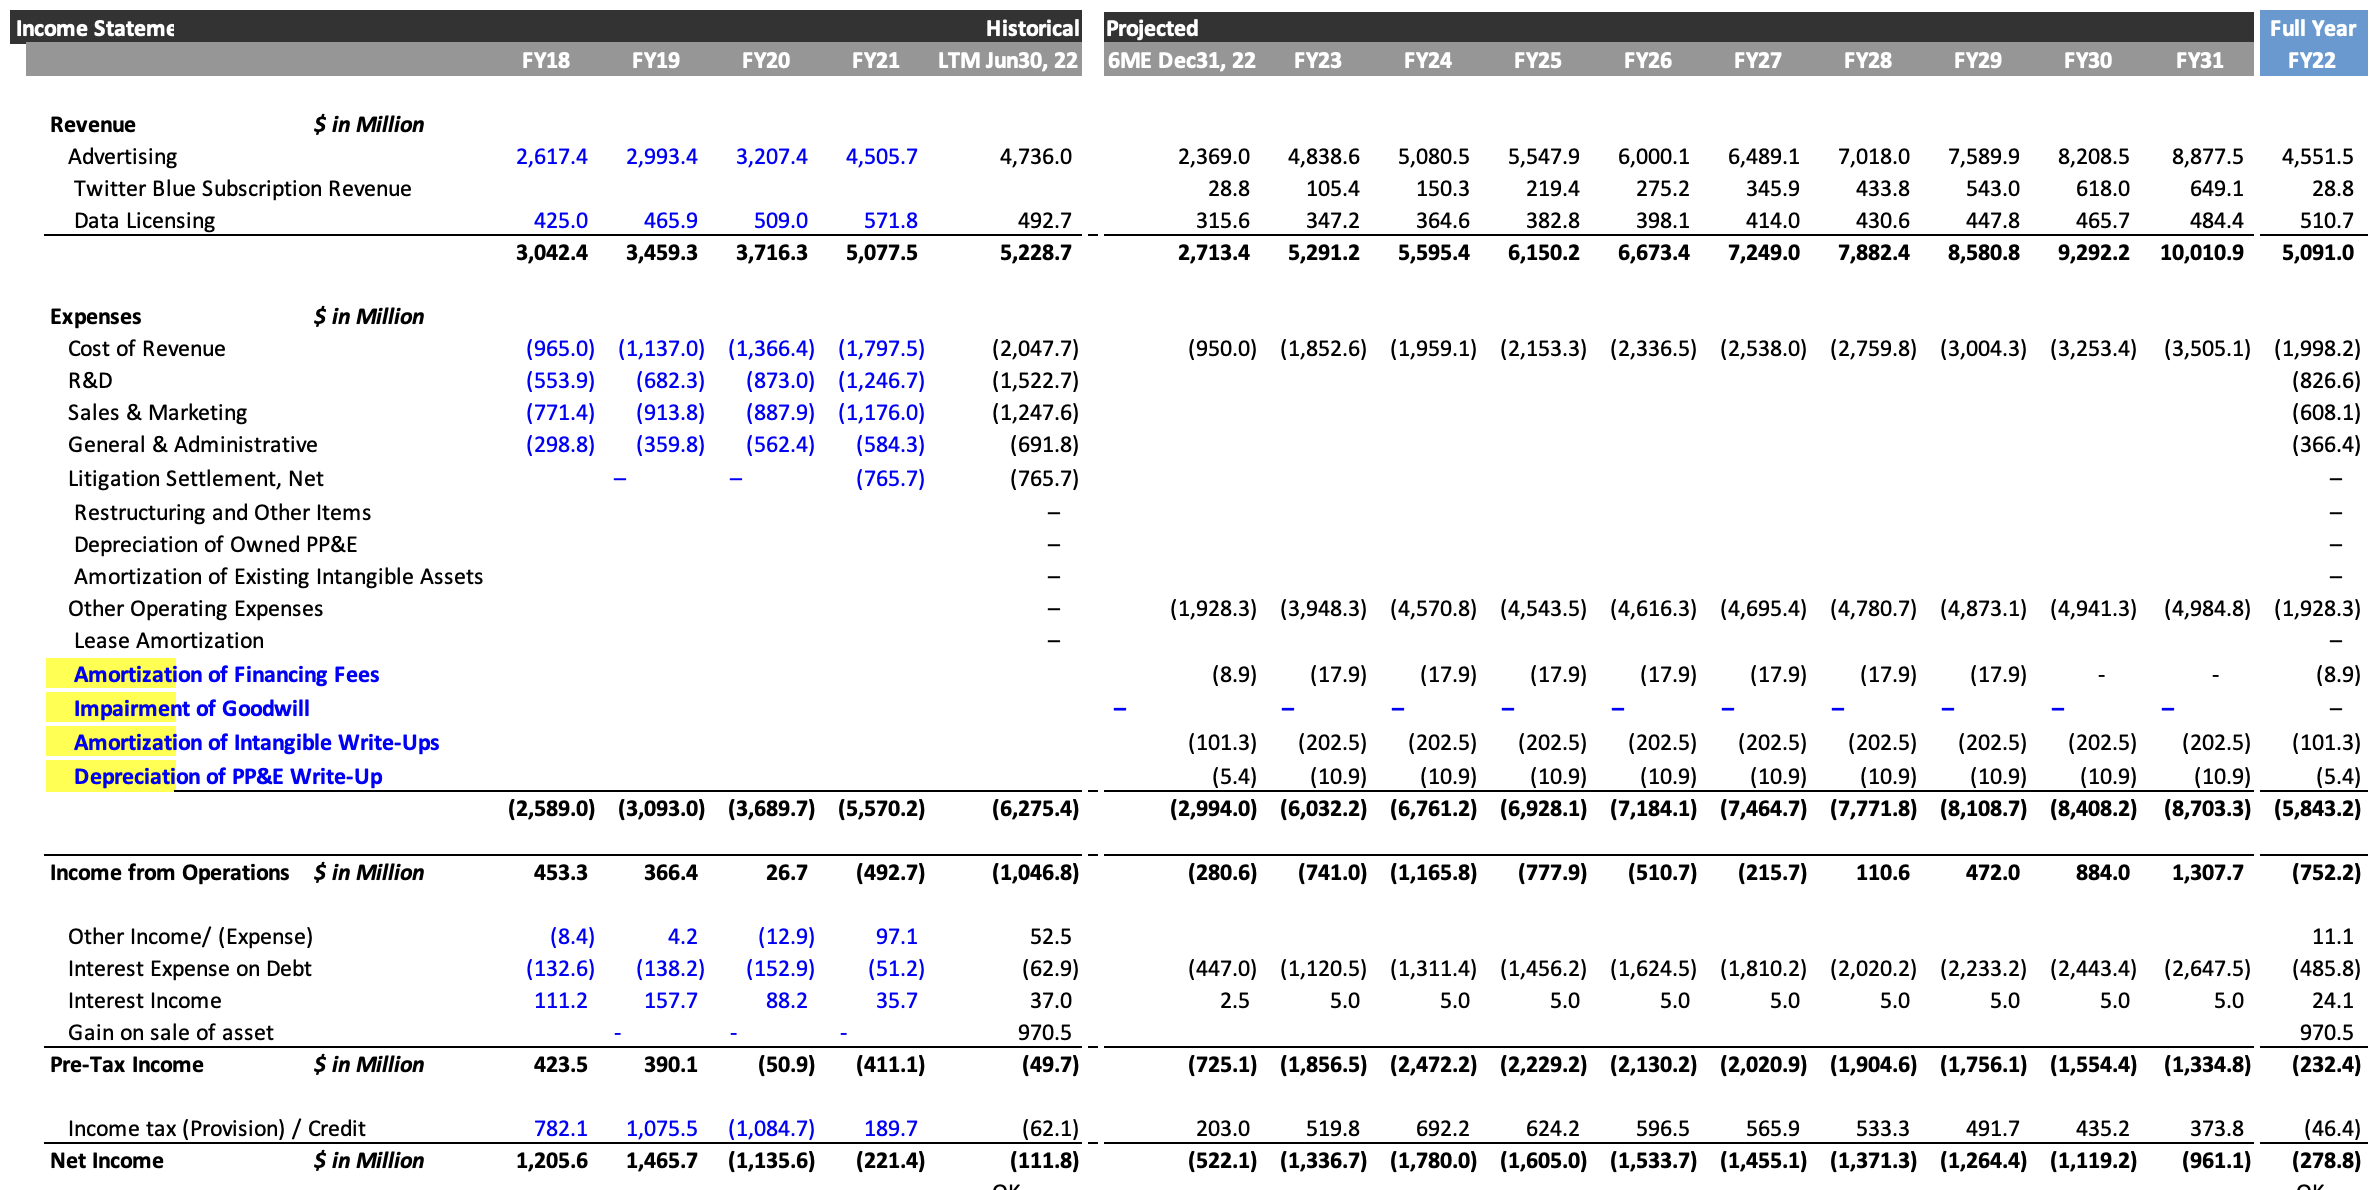
In the downside case, revenue grows only to about $10.0 billion by FY31. Operating losses continue through FY27, and the small operating profits that follow are swamped by interest, which climbs from $486 million in FY22 to $2.6 billion in FY31 as debt grows. Twitter loses money every year of the forecast.
Returns
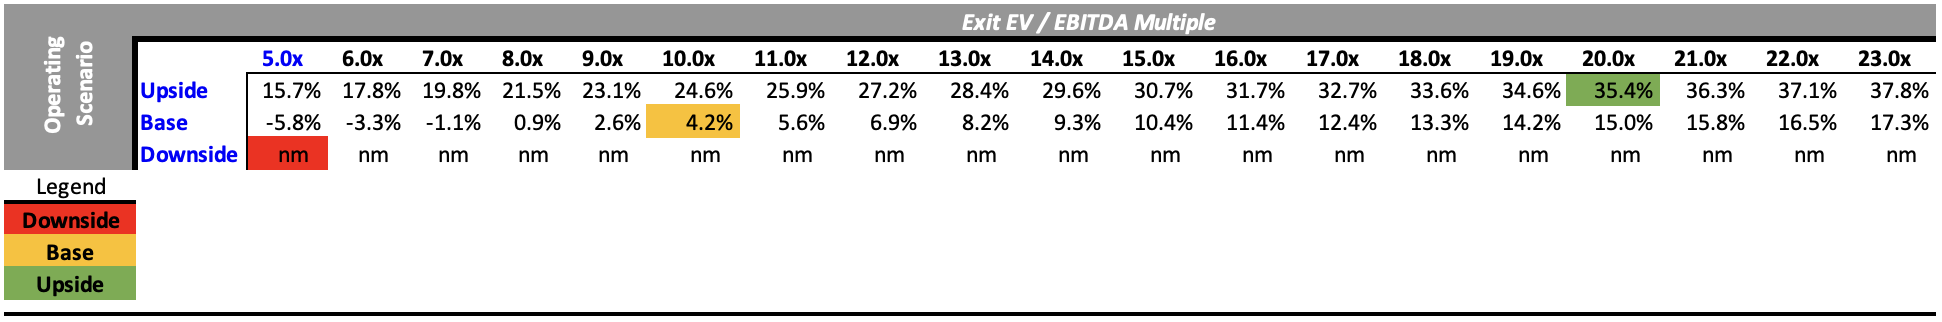 Note: nm means not meaningful; the downside returns are negative at every multiple.
- Base. At my base exit multiple of 10x, the equity returns 4.2% a year. Even at 23x, the highest multiple I tested, it reaches only 17.3%.
- Upside. The upside case clears 20% at an exit multiple of about 8x and reaches 35.4% at 20x. Even at a 5x exit it returns 15.7%, close to what the base case earns at 23x. A high exit multiple cannot rescue the base plan; Musk needs Twitter to beat it by a wide margin.
- Downside. Returns are negative at every multiple, so the equity loses money.
Four things hold the return down:
-
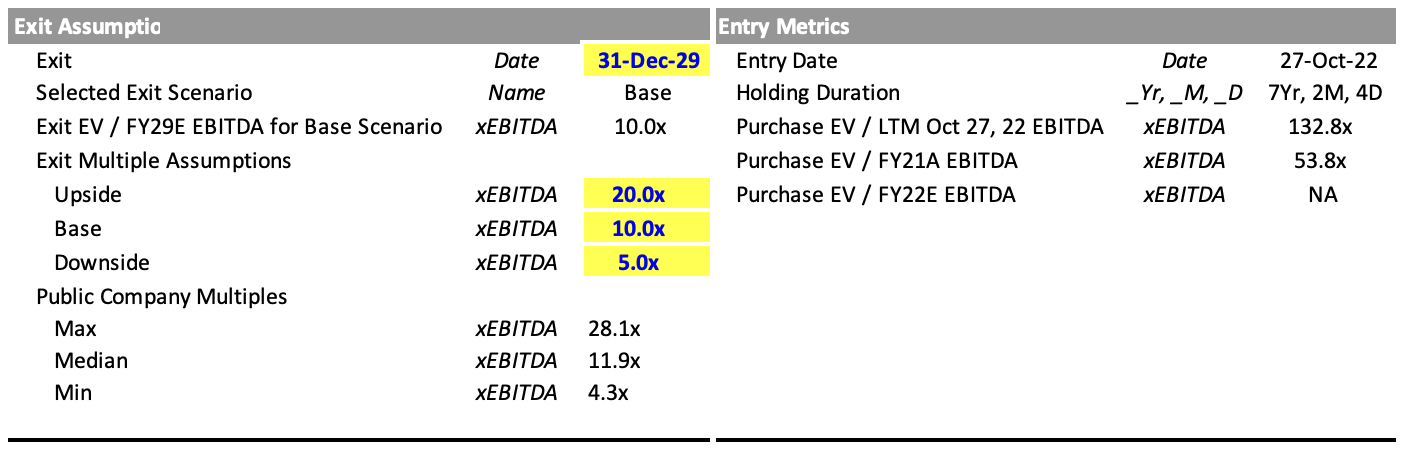
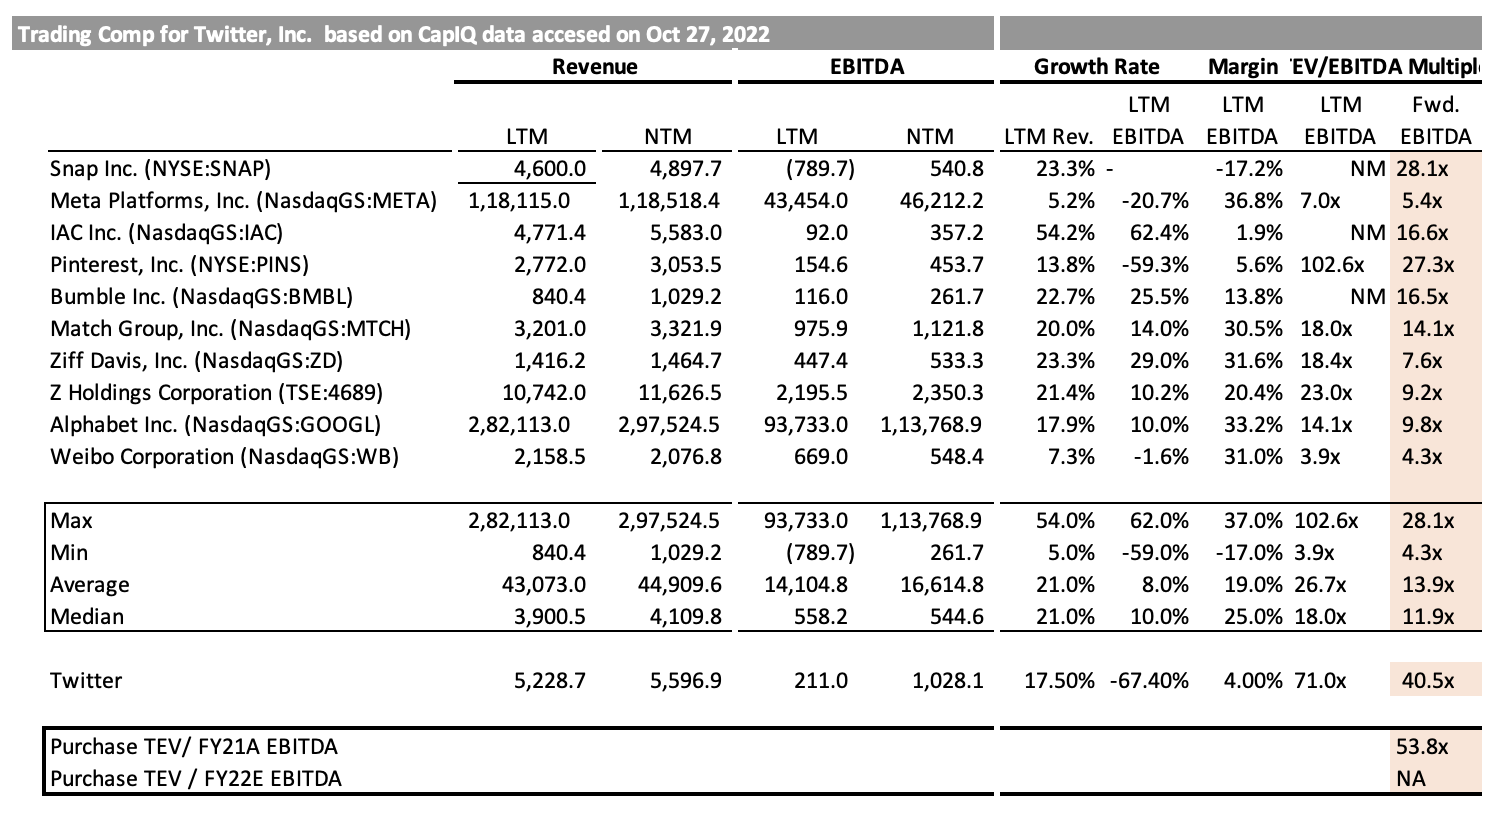
The entry price. Musk paid about 54 times Twitter’s FY21 EBITDA. Comparable companies traded at 4.3x to 28.1x forward EBITDA, with a median of 11.9x.
- The debt. The $12.5 billion of acquisition debt is about 15 times EBITDA. Interest and repayments absorb most of the operating cash flow; in my base case, the equity sees positive cash after debt service only from FY27.
- The growth already assumed. My base case already assumes revenue growth and margins near the top of what I consider realistic for a social media company. ARPU fell in parts of the historical period, and if Musk’s own allegations about fake accounts are right, part of the mDAU base is not real.
- The exit. An IPO exit carries uncertainty about both timing and valuation, and both weigh on the return.
What Musk’s behavior says
An IRR below 20% cannot tell me what motivated Musk. His behavior can. A buyer who valued Twitter above $54.20 a share for its cash flows would have closed quickly. Musk instead sent three termination letters, on July 8, August 29 and September 9, each on a different legal ground: spam data, the Zatko disclosures and Zatko’s severance payment. He agreed to close only on October 3, with a trial in the Delaware Court of Chancery two weeks away. That is the behavior of a buyer who, once markets fell, no longer valued the company at the price he had offered, and who closed because the alternative in court looked worse.
That leaves non-financial motives as the best explanation for the April price: free speech, which Musk names, and influence over a platform he uses every day. His attempts to walk away also put a ceiling on those motives. Once technology stocks fell, the value he placed on them no longer covered the gap between his price and Twitter’s investment value. Whether those motives survive the economics is the next question.
Free speech: what I will track
Musk closed the deal ten days before I published this post, so I have no post-acquisition data to test the free-speech motive. I will track three measures:
- Reinstated accounts: how many previously banned accounts return.
- Moderation rules: changes to Twitter’s written content policies and how they are enforced.
- Advertiser spend: whether major advertisers stay.
If moderation loosens and advertisers stay, the free-speech motive gains support. If advertisers leave and Musk tightens moderation to win them back, my LBO math explains why.
Conclusion
As an investment, Twitter at $54.20 a share does not work. My base case returns about 4% a year, close to a risk-free bond, and only a large operating outperformance gets the equity to a buyout-level return. Musk’s three attempts to walk away tell the same story from the other side.
Non-financial motives, led by the free speech Musk names, are what fit the price. The same arithmetic limits them: with $12.5 billion of debt and 89% of revenue from advertising, Twitter cannot afford to lose its advertisers. Free speech at this price has to pay for itself. Musk once said, “When something is important enough, you do it even if the odds are not in your favor.” On Twitter, the odds are now measurable.
Appendix
A1. Deal financing, signing vs. closing
Instruments Original commitments (April 25 signing) Changes before closing Final financing (my best estimate for closing) Margin loan Up to $12.5 billion, backed by Tesla shares Cut to $6.25 billion on May 5, then terminated on May 25 Zero Debt Up to $13 billion: senior secured term loan $6.5 billion, senior secured revolver $0.5 billion, senior secured bridge $3 billion, senior unsecured bridge $3 billion. Banks planned to sell all but the revolver in the secondary market No change $12.5 billion acquisition debt plus a $0.5 billion revolver Elon Musk, new equity Up to $21 billion Raised to $33.5 billion by May 25; Reuters reported that this included his existing stake and the co-investors’ money About $22.2 billion of the $33.5 billion commitment Elon Musk, equity rollover About $3.96 billion (73.1 million shares at $54.20) No change About $3.96 billion Other sponsors, new equity Zero $7.14 billion committed by May 5 $7.14 billion Other sponsors, equity rollover Zero About $2.27 billion (shares of QIA and Prince Alwaleed bin Talal at the offer price) About $2.27 billion Total About $50.5 billion About $48.6 billion
This table tracks public commitments. My model’s sources and uses totals about $50.8 billion: it leaves out the undrawn $0.5 billion revolver, adds about $2.2 billion of Twitter’s excess cash, assumes about $0.6 billion more rollover from other investors, and assigns more of the fresh equity to Musk.
A2. A roller coaster timeline
March to April 2022: Musk, the corporate raider powered by free-speech absolutism
- Mar 14: Musk’s stake crossed 5%.
- Apr 4: Musk disclosed a 9.2% stake in a Schedule 13G filing.
- Apr 5: Musk agreed to join the board and not to own more than 14.9% of the company.
- Apr 9: Musk decided not to join the board.
- Apr 14: Musk proposed to buy all outstanding shares at $54.20 each, a 38% premium over the price before his stake was disclosed. The proposal was conditional on financing and due diligence.
- Apr 15: The board adopted a shareholder rights plan (a poison pill).
- Apr 21: Musk disclosed $46.5 billion of financing commitments and said he was considering a tender offer.
- Apr 25: The merger agreement was signed. Musk had dropped the financing and due diligence conditions.
May 2022: markets take the shine off free-speech idealism
- May 4: The Fed raised the federal funds rate by 50 basis points, with CPI inflation above 8%. Technology stocks fell, and a stronger dollar hit multinationals.
- May 5 to May 25: The margin loan shrank and then ended, replaced by more equity from Musk and new commitments from co-investors. With Tesla’s share price falling, a margin loan at roughly 20% loan-to-value would have needed ever more Tesla shares as collateral.
June to September 2022: Musk, the reluctant buyer
- Jun 6: Musk’s lawyers repeated their demand for data on spam accounts.
- Jul 8: First termination letter. Ground: Twitter had not provided the data Musk said he needed to assess spam accounts.
- Aug 29: Second termination letter. Ground: Twitter had not disclosed the allegations in Peiter Zatko’s whistleblower complaint, covering FTC compliance, data center resilience, intellectual property and demands from the Indian government.
- Sep 9: Third termination letter. Ground: Twitter’s $7.75 million severance payment to Zatko, which Musk argued breached the merger agreement.
October 2022: the reversal and the close
- With Twitter’s lawsuit for specific performance heading to trial in the Delaware Court of Chancery, Musk faced a weak case. He had waived due diligence and secured financing that did not depend on it, so claiming that spam data was essential to closing was hard to sustain. Walking away would also have invited shareholder lawsuits, since he had pushed his way into the deal against a board that adopted a poison pill to stop him. And it suited Musk to close on the original terms: renegotiating the price would have let the banks reprice the loans. As a side note, I find it reassuring that under a functioning rule of law, even the world’s richest man has to keep his word.
- Oct 3: Musk proposed to close on the original terms.
- Oct 27: The deal closed.